


Published:
Apr 7, 2016
Updated:
Oct 10, 2026

The prospective treatment method vs. the cumulative catch-up adjustment method of applying contract modification treatment under ASC 606.

Contract Modifications Part I introduced contract modifications and described the steps to determine whether a contract modification should be considered a separate contract. First, an entity determines whether a change to a contract qualifies as a contract modification. Second, the entity determines whether the change meets the requirements for treatment as a separate contract. A contract is considered separate when the change comprises of the addition of distinct goods or services at a price comparable to their standalone selling prices. This article addresses proper accounting treatment for modifications that are not treated as separate contracts.
If the contract modification is not considered a separate contract, the modification is combined with the original contract. There are two methods to account for these contract modifications. An entity should choose the method that most appropriately aligns with the facts and patterns of the modified contract. The accounting model for contract modifications depends on the nature of all remaining goods and services at the time of the modification (not just those added by the modification).
If the remaining goods and services are distinct from those in the original contract, but the modification does not meet the other separate contract criteria (i.e., the additional goods are not sold at a price comparable to their standalone values), the entity treats the original contract as terminated and accounts for both the original contract and the modifications together as a newly created contract (Accounting Standards Codification (ASC) 606-10-25-13). Revenue already recognized on the original contract is not adjusted. All remaining transactions are accounted for on a prospective basis: unrecognized consideration is allocated to the remaining performance obligations.
Example A: Prospective Treatment with an Equipment Delivery Contract
On January 1, 20X1, Equipment Company entered into a contract with Knickknack Maker to sell twelve units of manufacturing equipment used for producing keychains for $1,000 each (for a total contract price of $12,000). The agreement outlines that Equipment Company will ship one unit of equipment every month for one year, starting on January 1, 20X1. Revenue of $1,000 per unit is recognized on delivery. On September 1, 20X1, after delivery of the first eight units, Equipment Company agrees to a contract modification to deliver six units of equipment used to assemble water bottles. These items are distinct from the keychain units and are normally sold at $1,200 per unit. However, Equipment Company will sell these units to Knickknack at $500 each—this price is not comparable to the standalone selling price. Equipment Company will continue to recognize revenue from each unit separately on delivery. Equipment Company concludes that the delivered keychain equipment units are distinct from those still undelivered.
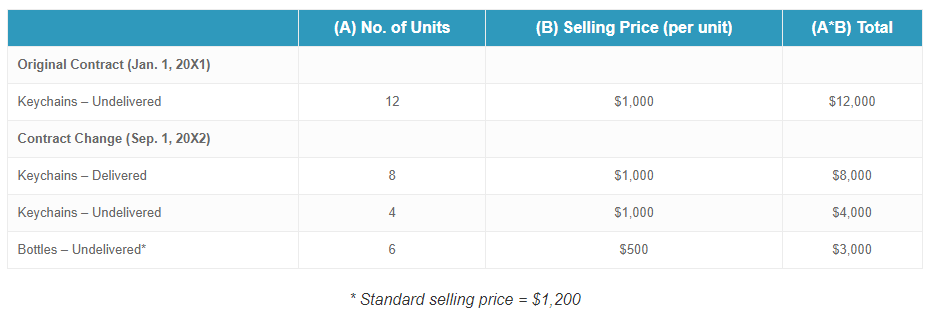
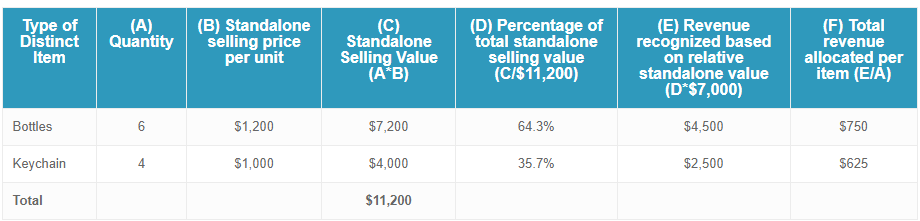
This contract modification should not be treated as a separate contract. Although there are additional, distinct goods being promised by Equipment Company, the price of those additional goods is not comparable to their standalone selling price. The original contract is considered terminated, but the $8,000 of revenue recognized up to this point on the already delivered units will not be adjusted. Instead, the performance obligations from the original contract and the obligations from the modification combine to create a new contract (with a total value of $7,000). Under the new contract, revenue is allocated to each item to be delivered based on its relative standalone selling price. As such, Equipment Company will recognize $750 for each bottle-maker and $625 for each piece of keychain equipment. (For more information, see Standalone Selling Prices.)
If the remaining goods and services are not distinct, the entity combines the increase or decrease of goods or services with the original contract’s promised goods or services to create a single performance obligation that is partially satisfied at the date of the modification. The entity adjusts revenue previously recognized to reflect the changes of the modification to the transaction price. This ensures that revenue recognized measures progress toward completion of the performance obligation (on a cumulative catch-up basis).
Example B: Cumulative Catch-Up Adjustment with a Construction Contract
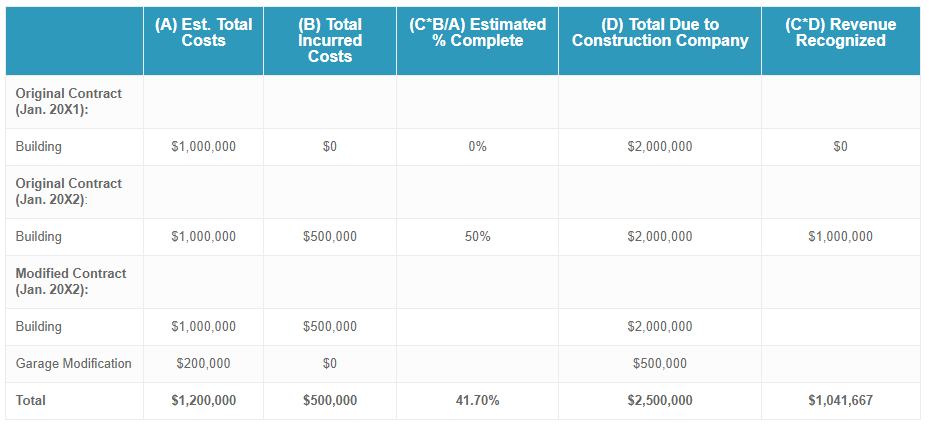
Construction Company agrees to build an apartment complex for Grump Company on January 1, 20X1. The building will take 24 months to complete and will be built on land owned by Grump Company. Construction Company will receive consideration of $2 million. Construction Company accounts for the goods and services provided as a single performance obligation satisfied over time. It also determines that the most appropriate method to measure the progress of completion is through the input measure of costs incurred. Construction Company expects total costs to total $1 million. By January 1, 20X2, Construction Company had incurred $500,000 in costs related to the project and measured its progress toward completion at 50 percent. Construction Company has accordingly recognized revenue of $1 million to date. On this same date, Grump Company requested a change in the scope of the contract: to increase the size of the parking garage. The parties agreed that an additional $500,000 will be paid to Construction Company for this change. Construction Company estimated it would incur additional costs of $200,000 as a result of the changes. It is also estimated that the changes will require an additional 6 months to complete construction. An analysis concludes that the additions are not distinct from the goods and services promised in the original or now-modified contracts. Therefore, the additional goods and services are part of the same performance obligation from the original contract.
Guidance for contract modifications under ASC 605 varied between industries but was most extensive for change orders and claims for construction- and production-type contracts (ASC 605-35). This shares some similarities with the guidance under ASC 606. As most other industries did not have as extensive authoritative 605 guidance, entities relied on guidance from accounting firms and followed their own, internally generated policies. Under ASC 606, entities need to critically evaluate their longstanding practices and policies. In practice, this has led to varying degrees of change in accounting policies, depending on how closely an entity’s historical accounting for contract modifications aligned with ASC 606.
Construction- and production-type industries generally did not experience significant changes in accounting for contract modifications, as ASC 605-35 contained similar concepts. ASC 605-35 has similar requirements for additional, distinct promised goods and services at a comparable price in order for a change to be a separate contract. However, all entities will need to carefully examine modified contracts that were considered completed under ASC 605 because performance obligations associated with those modifications may be considered unsatisfied under ASC 606 (for more on this, see Contract Modifications – The Hindsight Expedient).
ASC 606 provides authoritative guidance to a subject that, in many industries, had none. Under legacy guidance in ASC 605, many entities relied on firm guidance and other non-authoritative sources to develop accounting policies for contract modifications. The adoption of ASC 606 required entities to review longstanding policies and practices to ensure alignment with authoritative guidance.
If the goods or services remaining after a contract modification are distinct from those in the original contract, but are not provided at comparable standalone selling prices, the original contract is treated as terminated; the original contract’s remaining performance obligations and the modification are accounted for as a single, partially completed contract without any adjustments to revenue. If there are no distinct goods or services provided, the modification is combined with the original contract by adjusting revenue on a cumulative catch-up basis.
During adoption, many companies encountered impracticalities in applying the transition guidance pertaining to contract modifications. Many entities found it costly and operationally challenging to retrospectively apply this guidance to all contract modifications because they have numerous decades-long contracts with multiple modifications. The Financial Accounting Standards Board (FASB) provided the hindsight practical expedient to ease the application of the transition guidance from ASC 605 to ASC 606.
This article was originally published in April 2016 during the implementation of ASC 606. While the discussion reflects an adoption-period perspective, the technical guidance and conclusions regarding prospective and cumulative catch-up accounting for contract modifications remain consistent with current GAAP.